Tax-Saving Investment Options in 2026: A Complete Guide (With Payroll Software Tips)
Taxes are the one guest who always shows up uninvited. The good news is that the IRS also hands you several legal ways to shrink that bill. Most of them run straight through your paycheck, which is where payroll software earns its keep. This guide covers the main tax-saving investment options for 2026 using official IRS limits. It also shows how employers can make them easy to use.
Top Tax-Saving Investment Options for 2026
401(k), 403(b), and 457(b) Plans
The IRS raised the 2026 employee limit for these plans to $24,500, up from $23,500. Workers 50 and older can add an $8,000 catch-up, for a total of $32,500. Ages 60 to 63 can make a higher catch-up of $11,250 if their plan allows it.
There is one new twist. Starting January 1, 2026, certain higher-paid workers must make catch-up contributions as Roth contributions.
Traditional and Roth IRAs
The 2026 IRA limit rises to $7,500, with a $1,100 catch-up for people 50 and older. Income matters, though. If you are single and covered by a workplace plan, the traditional IRA deduction phases out between $81,000 and $91,000. Roth IRA eligibility phases out between $153,000 and $168,000 for single filers.
Health Savings Accounts (HSAs)
An HSA pairs with a high-deductible health plan. The 2026 limits are $4,400 for self-only coverage and $8,750 for family coverage. People 55 and older can add $1,000. Used for qualified medical costs, it is a savings account with a tax-free cape.
Flexible Spending Accounts (FSAs)
A health FSA allows up to $3,400 in 2026, and some plans let you carry over $680. A dependent care FSA allows $7,500 per household. Fair warning: unspent FSA money is generally forfeited at year-end. Treat it like a gift card with an expiration date.
|
Account |
2026 Limit |
|
401(k), 403(b), 457(b) |
$24,500 |
|
IRA (traditional or Roth) |
$7,500 |
|
HSA (self-only / family) |
$4,400 / $8,750 |
|
Health FSA |
$3,400 |
|
Dependent care FSA |
$7,500 |
How Payroll Software Supports Tax-Saving Investments
Most of these accounts run on payroll deductions. HSAs and FSAs, for example, are usually funded with pre-tax dollars through payroll. One wrong setting, and an employee overshoots a limit or misses a tax break.
Good payroll software helps in four ways:
- Keeps limits current. Employers can update the 2026 figures so deductions stop at the cap. Experts note that updating payroll systems helps avoid compliance issues.
- Handles pre-tax deductions. It separates pre-tax and after-tax contributions correctly on every pay stub.
- Connects with HR system software. Benefit elections flow into payroll without retyping, so fewer typos sneak in.
- Pulls hours from an attendance management system. Accurate time data means accurate gross pay, and contributions calculate from the right number.
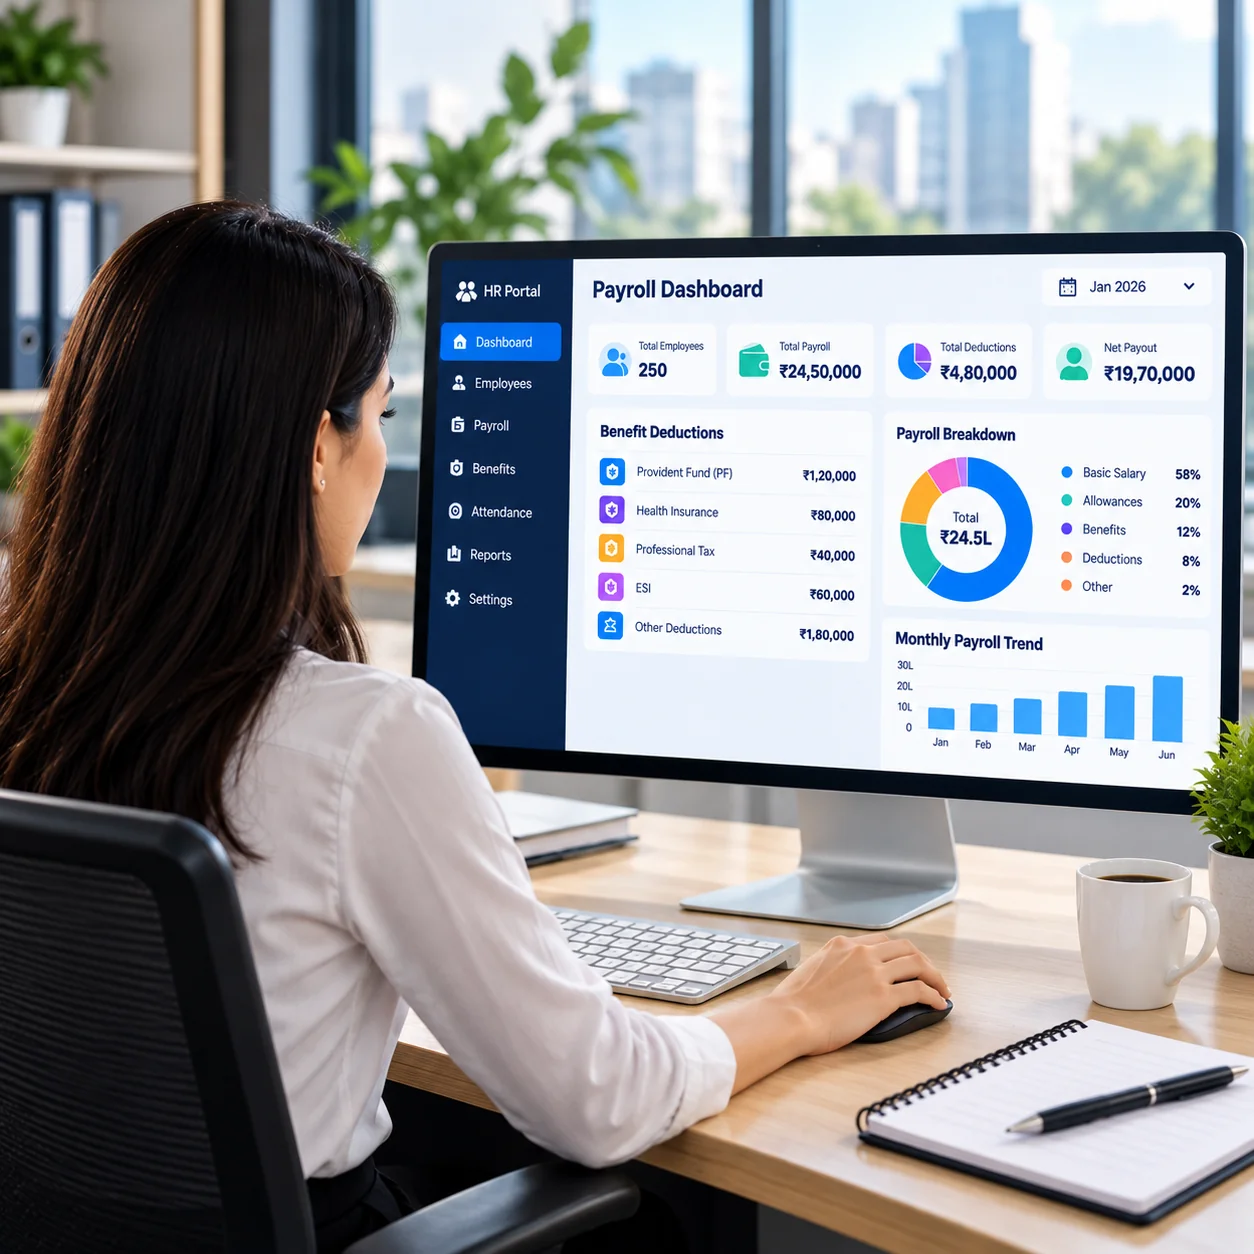 Tax-Saving Investments 2026: Payroll Software Guide
Human resource management software adds the people side. It stores benefit enrollments, sends open-enrollment reminders, and keeps records in one place.
Rewards count too. Employee recognition programs often include cash or gift cards, and cash awards are generally treated as taxable wages. Running them through payroll keeps records clean and surprises rare. Check with a tax professional for your specific situation.
Your 2026 Action Plan
Keep it simple:
- Capture your employer match first. It is the easiest return you will find.
- Check HSA eligibility. You need a qualifying high-deductible health plan.
- Plan your FSA spending early. Do not let December become a shopping spree for bandages.
- Talk to a CPA. Income limits and phase-outs vary by situation.
Final Thoughts
Tax-saving investing is not about tricks. It is about using the accounts the IRS already gives you, in the right order, with the right numbers. Employers can make that easier with reliable payroll software and connected HR tools. Employees can help themselves by reviewing contributions at least once a year. Small, steady steps beat a last-minute scramble every time.
This article is for general information only and is not tax or financial advice. Consult a qualified tax professional.